Services · Retirement Tax Planning

Retirement tax planning in Sarasota

Keep more of what you’ve saved. Retirement income is taxed differently — and planning ahead makes an enormous difference. We help retirees and pre-retirees in Sarasota navigate RMDs, Roth conversions, Social Security timing and Medicare surcharges to keep taxes down throughout retirement.
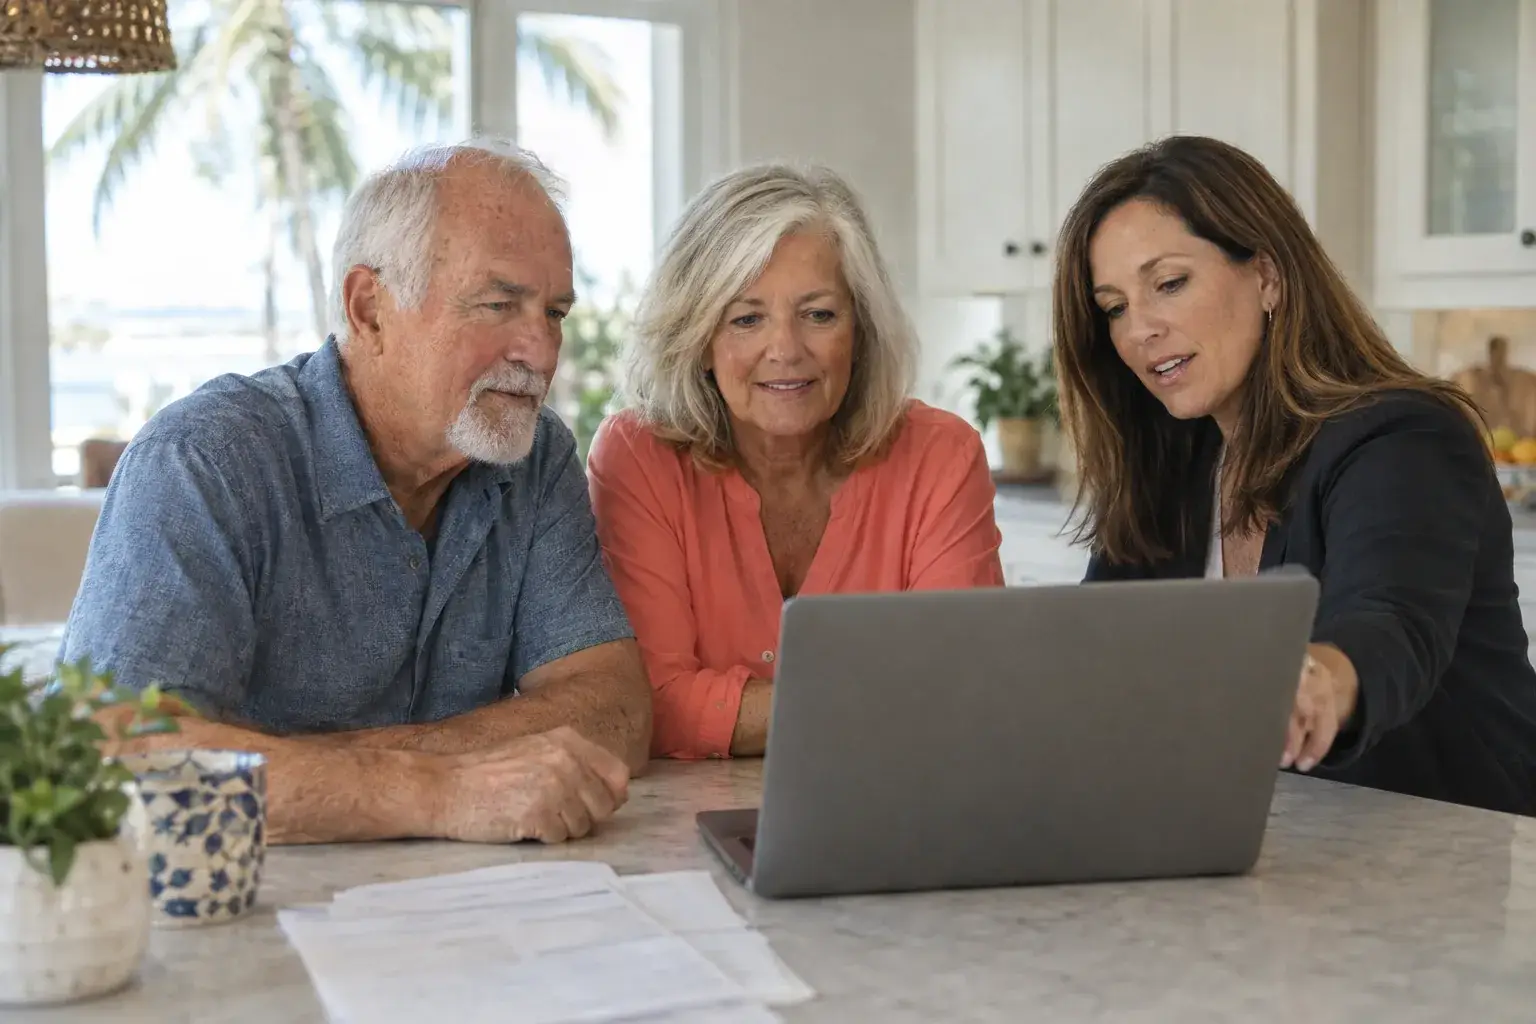
Retired couple reviewing retirement accounts on a laptop with a tax advisor

The short answer

What is retirement tax planning?

Retirement tax planning decides the order and timing of your income in retirement — which accounts you draw from, when you claim Social Security, whether to convert to Roth, and how required minimum distributions will land — so your lifetime tax bill is lower, not just this year’s.

At a glance

What it covers

What retirement tax planning includes

Required Minimum Distribution (RMD) planning

Planning the years before and after RMDs begin so withdrawals don't push you into higher brackets.

Roth IRA conversion strategies

Using lower-income years to move money into tax-free Roth accounts, one bracket at a time.

Social Security income optimization

Coordinating your claiming age with other income so less of your benefit is taxed.

IRMAA Medicare surcharge planning

Watching the income thresholds that raise Medicare Part B and D premiums two years later.

Qualified Charitable Distributions (QCDs)

Giving directly from an IRA so the gift counts toward your RMD without adding to taxable income.

Survivor and estate considerations

Planning for the year a spouse passes, when filing status and brackets change.

The window before RMDs begin

Under current law, required minimum distributions from traditional IRAs and most workplace plans begin at age 73 for people born from 1951 through 1959, and at 75 for people born in 1960 or later. The years between retirement and that age are often the lowest-income years of your life.

That window is valuable. Withdrawals or Roth conversions taken in those years can be taxed at lower rates than the forced distributions that come later, when RMDs stack on top of Social Security and any pension. We map those years out and decide how much to convert or withdraw each year, so the large balances don’t all arrive at once.
Retired man reading a letter on a shaded Florida porch

At a glance

Milestones that change your retirement taxes

59½

IRA withdrawals no longer face the 10% early-withdrawal penalty.

62–70

The range of ages to claim Social Security; timing changes taxes too.

65

Medicare begins; IRMAA looks back at income from two years earlier.

73 / 75

RMDs begin: 73 if born 1951–1959, 75 if born 1960 or later.
Couple sorting household financial papers on a screened Florida lanai

Social Security, Medicare and the hidden thresholds

Up to 85% of Social Security benefits can be taxable, depending on your other income. Medicare adds its own layer: if your modified adjusted gross income passes certain thresholds, you pay an income-related monthly adjustment amount (IRMAA) on Part B and Part D premiums, based on your return from two years earlier.

A large IRA withdrawal, a Roth conversion or a home sale can cross those lines. We watch them as part of the plan, so a decision that saves tax one year doesn’t quietly raise your Medicare premiums two years later.

Giving and the year a spouse passes

If you give to charity, a qualified charitable distribution lets you send money from an IRA directly to a charity once you are 70½ or older. The gift can count toward your RMD and stays out of your adjusted gross income, which can be worth more than an itemized deduction.

We also plan for the hardest year: when one spouse dies, the survivor generally files as single after the year of death, with narrower brackets on similar income. Planning conversions and withdrawals with that possibility in mind protects the surviving spouse.

Common mistakes

Mistakes we help you avoid

Letting RMDs set your bracket

Large pre-tax balances can force distributions that push you into higher brackets later. Planned withdrawals or conversions earlier can smooth that out.

Missing an RMD

Missed required distributions carry an excise tax. It can often be reduced if the shortfall is corrected promptly, but it’s better avoided.

Converting without watching IRMAA

A Roth conversion counts as income. Without checking the Medicare thresholds, a conversion can raise premiums two years later.

Giving with cash instead of a QCD

If you’re 70½ or older and give to charity, a qualified charitable distribution can be more tax-efficient than writing a check.

Planning only for two

When a spouse dies, the survivor generally moves to single brackets. Planning that ignores this can leave the survivor with a higher bill.

Who this is for

People within ten years of retirement, recent retirees between retirement and RMD age, retirees already taking RMDs, and couples planning for the surviving spouse.

Answers

Retirement Tax Planning: common questions

Under current law, 73 if you were born from 1951 through 1959, and 75 if you were born in 1960 or later. Your first RMD can be delayed until April 1 of the following year, but that can mean two distributions in one tax year.
It depends on your current bracket, your expected bracket later, Medicare thresholds and how long the money will stay invested. Conversions often make the most sense in the lower-income years between retirement and RMDs. We model it before you convert.
Florida doesn’t tax it, but up to 85% of your benefit can be subject to federal income tax depending on your other income.
IRMAA is an extra amount added to Medicare Part B and Part D premiums when income is above set thresholds. It’s based on your tax return from two years earlier, so planning income now affects premiums later.
Someone who looks at your whole picture: retirement accounts, Social Security, Medicare and investments together. We work alongside your financial advisor when you have one.

Other services

Explore related services
Pay less — legally, consistently, year after year.
Accurate, thorough, and filed on time — every time.
Smart structure. Lower taxes. More growth.
Florida’s real estate market deserves a real strategy.
Clean books. Clear picture. Better decisions.

Get started

Request a consultation

Tell us a little about your situation and we’ll be in touch within one business day.
  • This field is for validation purposes and should be left unchanged.

Next step

Ready to pay less and plan more?

Schedule a consultation and let’s build a tax strategy that works for your life in Sarasota.